

Updated October 4, 2026.
Contents
October 4, 2026 extension. New filings specify no combo maker rebate, with a stated October 19 start. Read the extension. The original analysis below retains its October 1 evidence and conditional results.
Updated October 1, 2026. The fee page announces a combo coefficient increase from 0.04 to 0.06 at 10 a.m. Eastern today. At 9:10 a.m., it still showed the old tables and a future notice. The calculations below use the announced curve, whose implementation we have not verified. The separate maker rebate proposal still has an intended October 6 start.
A maker supplies an order for another trader to accept. The trader who accepts it is the taker. A combo combines several outcome contracts into one position. Polymarket US's published standard maker schedule pays a $1.12 rebate on a 1,000-contract fill at 10 cents. That amount is the same for a standard contract and a combo.
At the proposed top maker rate of 15%, the standard fill would earn about $0.94. Under the announced October 1 combo curve, the combo would earn about $1.53. That rate ordinarily requires $200 million in prior-month maker volume, although other qualification routes exist. At this price, the lower maker tiers still earn less than the current formula.
The reversal comes from connecting two rules. The September 22 proposal replaces the standard maker formula with a share of taker fees. The current fee page puts combo makers on that standard formula while charging combo takers more. If the replacement covers those combo fills, some of that extra fee reaches the maker.
The proposal does not name combos, so their future coverage remains unresolved. Crypto, cross-category combos and block trades are outside this claim. The scope review records the evidence. The intended October 6 start remains subject to review. The opening amounts assume one credit rounded to cents, but the proposal does not specify actual credit rounding.
How the combo surcharge reaches the maker
Return to the 1,000-contract fill at 10 cents. The maker receives $1.12 under the current formula. The standard taker fee is $6.26. Under the announced curve, the combo taker fee becomes $10.19, up from $8.88 under the previous curve. The combo costs more because its taker fee includes a surcharge. The whole combo fee applies to the combo as a unit, not separately to each leg. These amounts follow the published formulas and October 1 notice.
That extra fee makes no difference to the maker's rebate today. Under the proposed fee share, a maker at the 15% rate receives 15% of the taker fee charged on the fill. The combo's extra $3.93 over the standard fee therefore adds roughly 59 cents to the calculated rebate. That is enough to turn the standard fill's decrease into a combo increase.
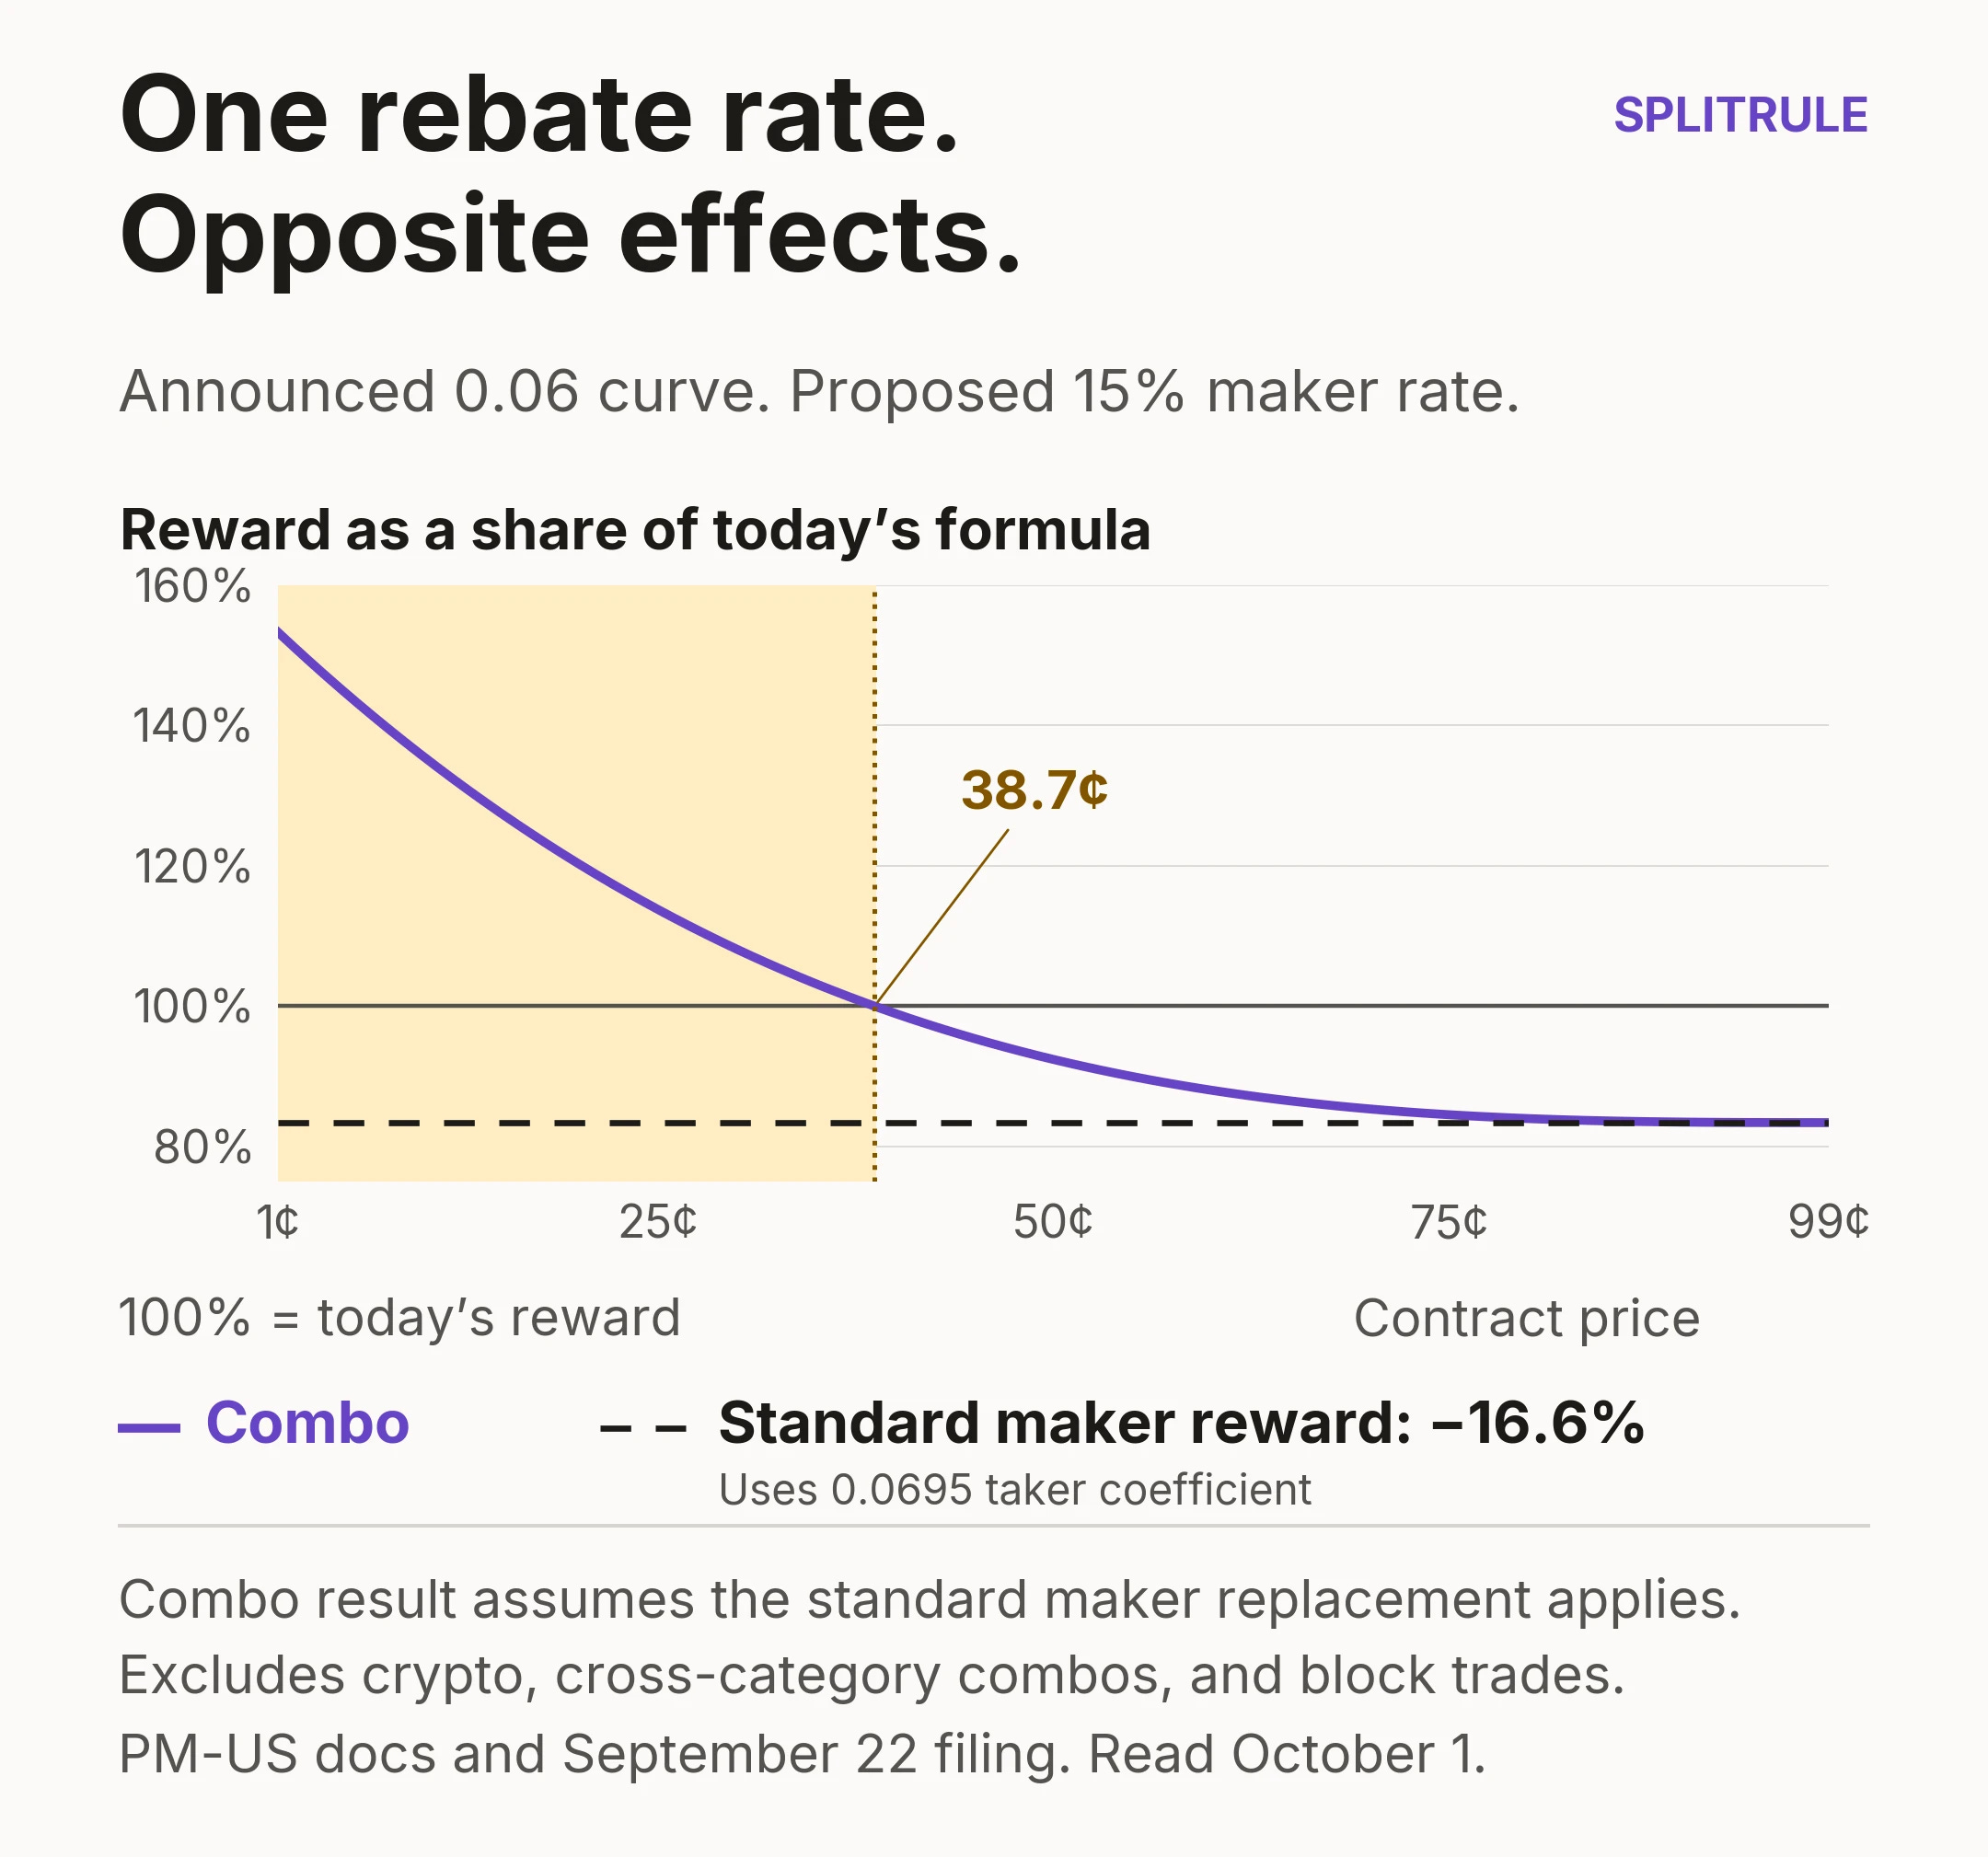
The question is how far that result extends beyond a 10-cent fill. The chart compares the proposed 15% reward with the current reward across contract prices. Its 100% line means the two formulas pay the same amount. A line above it means an increase, and a line below it means a decrease.
Maker rewards across contract prices. Splitrule calculations from the fee schedule and September 22 proposal.
The dashed line uses the standard taker coefficient of 0.0695. At the 15% maker rate, it stays at 83.4% of the current reward, a 16.6% decrease before rounding. The current maker reward and this taker fee vary with the same combination of price and quantity. Changing the price or quantity changes the dollars without changing that percentage decrease.
The combo line slopes downward because the surcharge is largest relative to the standard fee at low prices. Under the announced curve, it adds about 63% to that fee at 10 cents, versus about 11% at 50 cents before rounding. Below about 38.7 cents, the surcharge lifts the proposed top-tier reward above the old formula. Beyond that point, it still pays the maker more than a standard fill would, but less than the old reward.
Rounding near the crossing can turn a small decrease into an equal payment. Splitting an order into many small fills can also change the total. The derivation and payment examples explain why 38.7 cents is not an exact cutoff on an account statement.
The fee page read on September 30 announced a Table Tennis taker coefficient of 0.10 from 11:59 p.m. Eastern that day. That notice was absent at our October 1 read. Its removal does not establish implementation or cancellation. If the proposed 15% maker share applies there, it pays 20% more than today's 0.0125 maker formula before rounding. No source reviewed here states a separate Table Tennis maker rule. That result remains conditional, but it shows the same mechanism: higher taker fees can mean higher maker rewards under a fee share.
Why the maker's tier matters
The larger surcharge also changes the lower-tier result. At the proposed 10% maker rate, the formula can beat the current rebate below about 2.6 cents before rounding. The 5% rate still cannot. Both results assume that the proposed maker share covers these combo fills.
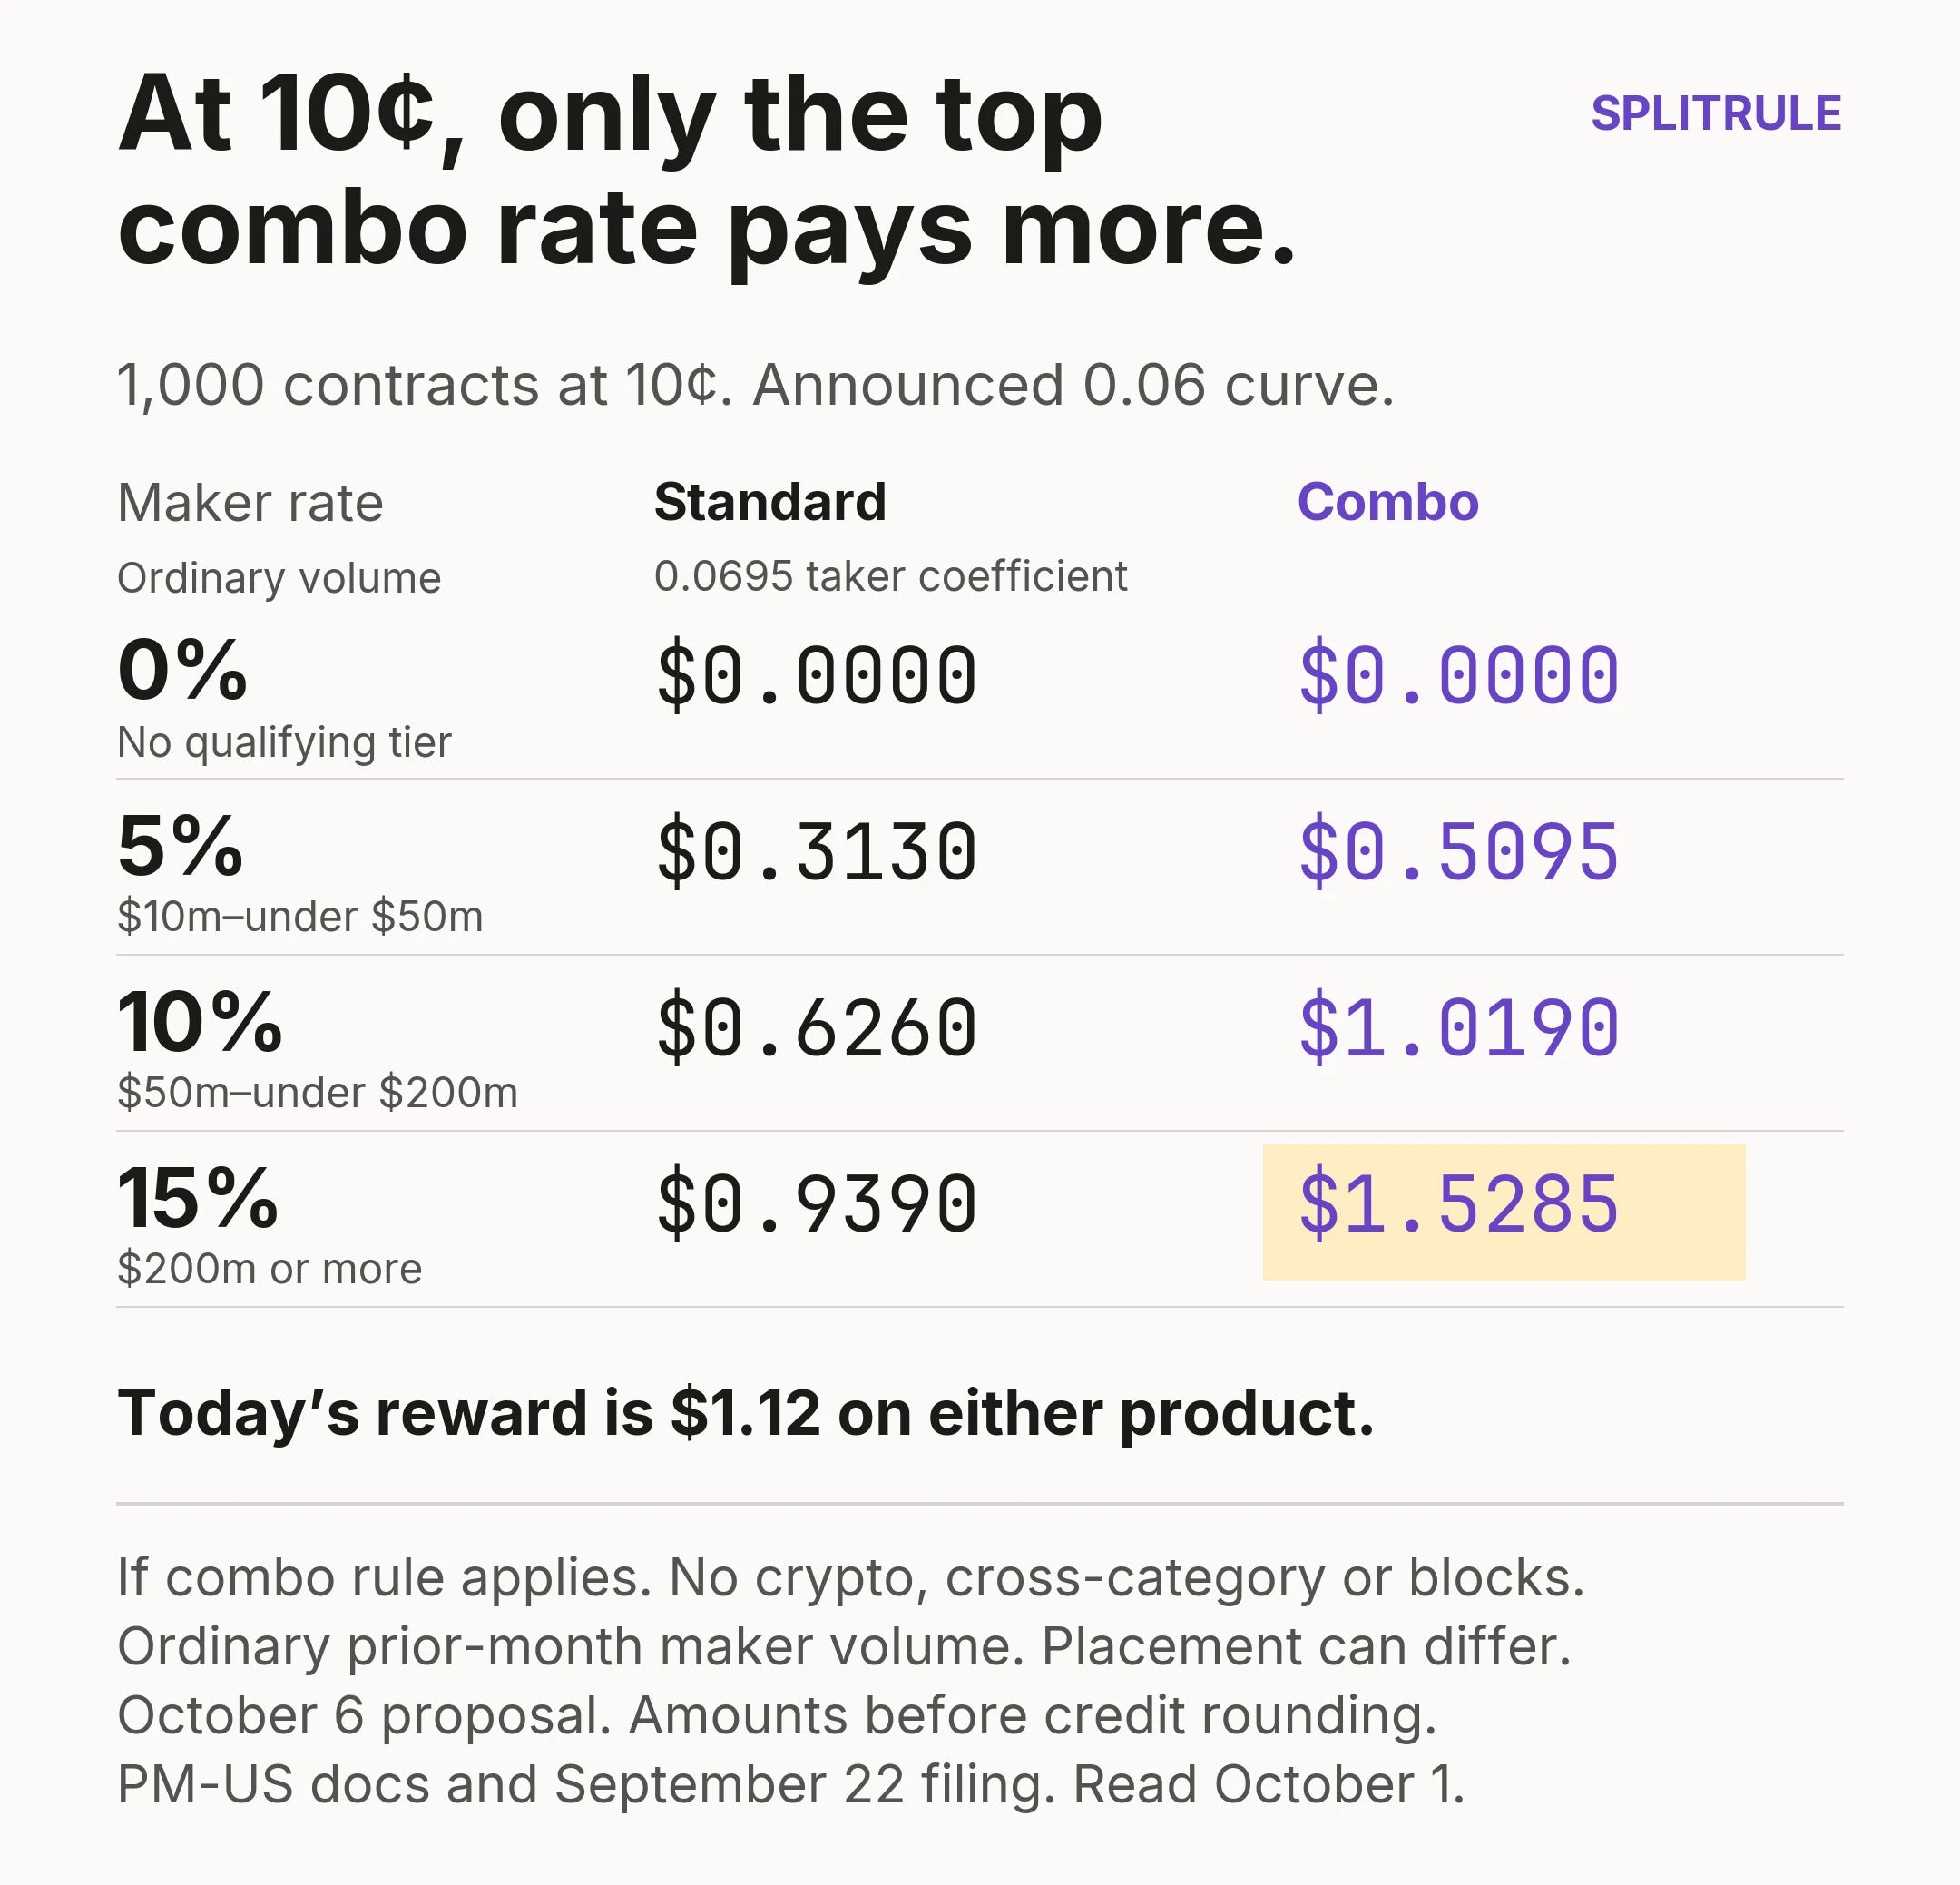
The second graphic returns to the same fill of 1,000 contracts at 10 cents. It changes only the assigned maker rate. Today's rebate is $1.12 in either column. The proposed amounts appear before credit rounding.
The same fill across maker tiers. Splitrule calculations from the fee schedule and September 22 proposal.
The ordinary maker tiers use the previous calendar month's maker volume. The rate starts at 5% for $10 million, rises to 10% at $50 million, and reaches 15% at $200 million. Accepted external volume can qualify a maker for a different tier. The first effective month also allows the preceding seven days of local volume scaled to a 30-day amount. The placement notes give the exact rule, and maker and taker volumes count separately.
Today's standard maker formula has no volume floor, although small fills can round to zero. Under the proposal, a maker who qualifies for no standard tier loses that rebate. At the 5% and 10% rates, the 0.0695 standard comparison pays 72.2% and 44.4% less before rounding. The 16.6% decrease is the best of those three standard-tier comparisons.
The assigned maker rate applies to the taker fees charged on that maker's fills, before taker rebates. A taker receiving more money back therefore does not reduce the maker's calculated reward on the same fill.
What this could mean for the trader paying the fee
The announced October 1 change raises the gross combo taker fee. The separate October 6 proposal would change how that fee is shared. A larger rebate could let a maker offer a better price while earning the same amount from the trade and rebate together. Competition might then pass some of that reward to the trader accepting the quote.
But the rebate alone cannot show that this happens. Makers may need the extra compensation for holding positions or trading just before prices move against them. Other liquidity rewards also affect what they can offer. This calculation measures one part of their compensation. It does not establish their profit or willingness to quote.
The taker's cost is the execution price plus the fee, less any taker rebate. The same filing reduces taker rebates in four previously rebated volume bands from $250,000 to below $50 million. Under ordinary placement, those takers keep less of their rebate. That comparison holds the fee curve fixed and comes on top of the announced combo fee increase. The methods show the four rate changes and placement limits.
A better quote helps only to the extent that it improves that total cost. The useful next question is whether quote competition offsets more of the combo surcharge where the proposed maker reward rises. This calculation points to low-priced combos at the 15% maker rate, plus a smaller region at the 10% rate. Answering that question requires execution evidence that this rule analysis does not provide.
Methods and sources
Finding decision, derivation and worked examples, source and prior-work review, claim audit and unresolved questions. The calculations use invented fills.
October 4 extension: no combo maker rebate in the October 19 schedule
Polymarket US's October 2 filings remove the condition that produced the possible combo gain in this article. Their stated start is October 19, 2026.
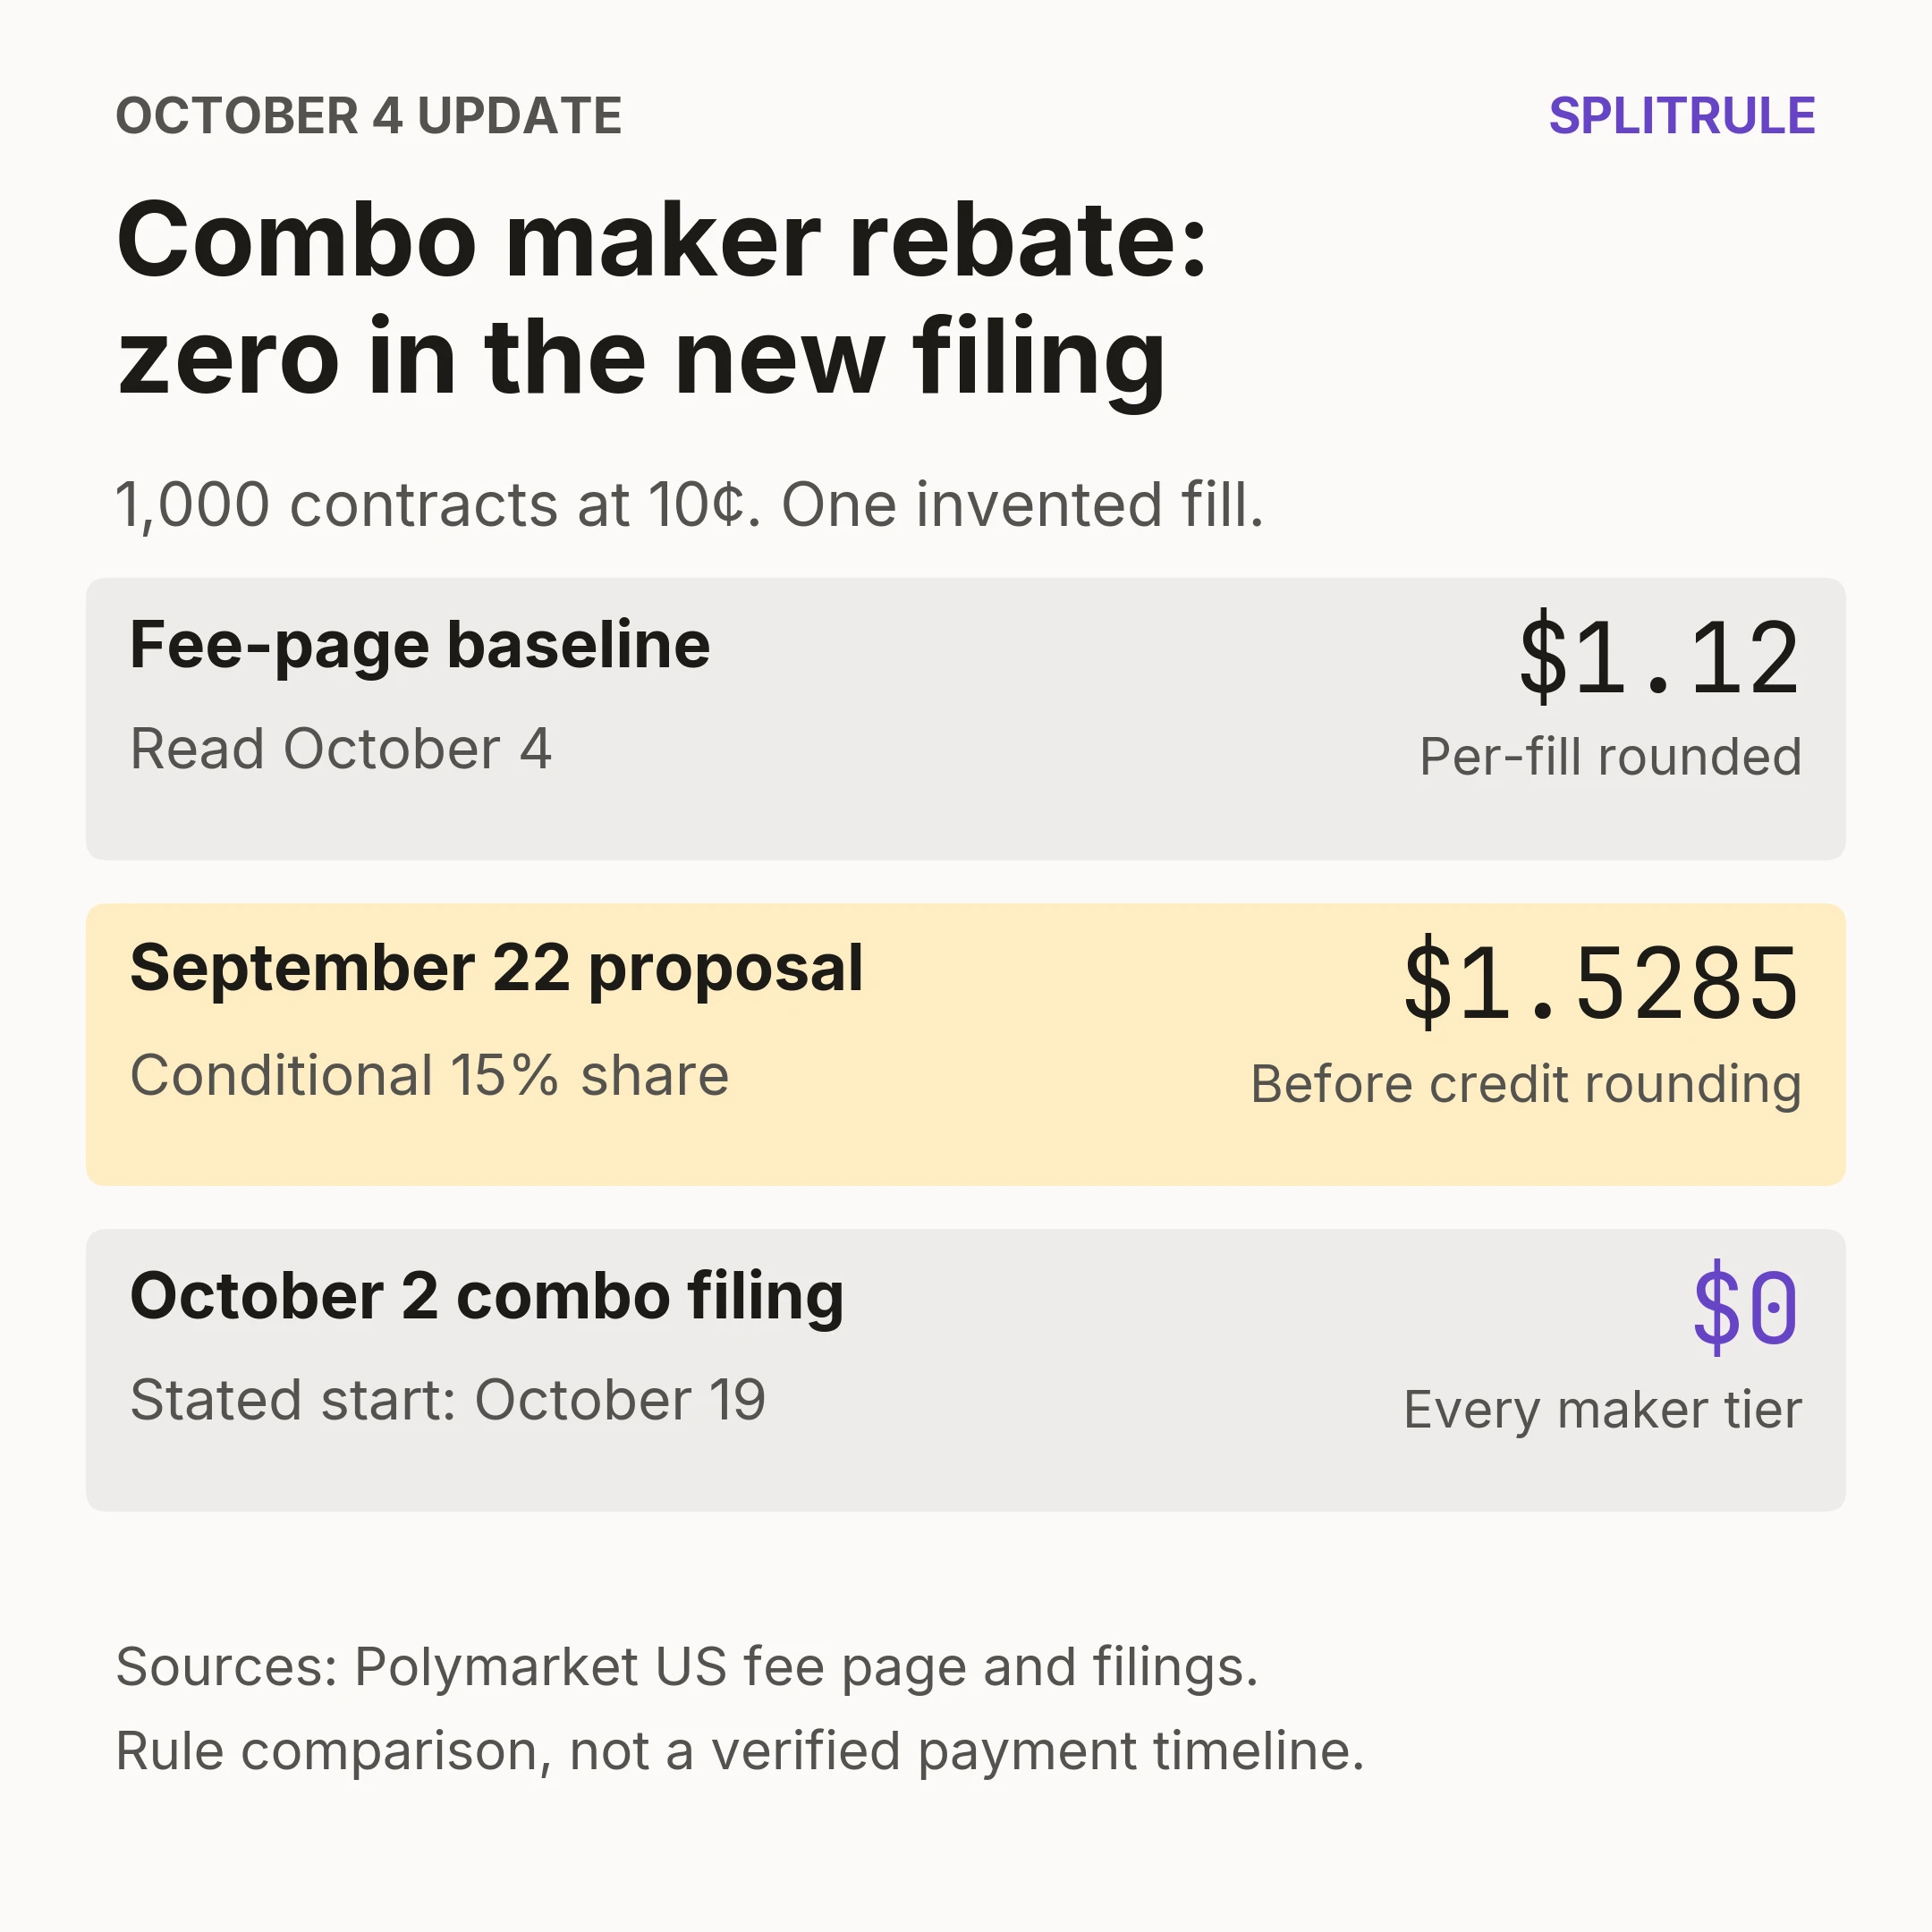
The combo filing sets the maker rebate to zero on all combo fills, regardless of tier. The maker fee is also zero. Under that rule, a higher combo taker fee sends no per-fill rebate to the maker. The earlier 38.7-cent crossover therefore does not apply.
For a new reader, the earlier argument was conditional: a share of a sufficiently large combo taker fee can exceed the old maker rebate. That arithmetic remains correct for the September 22 proposal and its assumed combo coverage. It does not describe the October 19 combo rule.
One invented fill under three rules. The middle amount assumes combo inclusion under the earlier proposal. The new filing excludes combos regardless of tier.
The separate maker filing changes the standard rebate to three coefficients. It no longer calculates that rebate as an exact share of the taker fee. Against the old formula, the top coefficient pays 16.8% less before rounding. For the same 1,000-contract standard fill at 10 cents, it gives $0.936, or $0.94 under the published per-fill rounding rule. Ordinary maker-volume thresholds remain $10 million, $50 million and $200 million, with placement exceptions.
The taker filing also states October 19. Its five rebate rates are 3%, 5%, 10%, 15% and 30%. Against the October 4 fee-page baseline, every previously rebated ordinary volume band receives a smaller share back. The new methods section compares all three schedules.
There is one unresolved timing question. The September 22 proposal targeted October 6, while the October 2 filings state October 19 and amend the older coefficient schedule. The reviewed public sources do not say whether the percentage proposal takes effect in between or is withdrawn. We therefore cannot establish an October 6–18 fee-share window. The October 4 fee page still lists the old maker rebate. It now describes the 0.06 combo taker curve as effective October 1. Neither statement resolves the future sequence.
The original analysis and graphics remain above as a dated explanation of the September proposal. Under the new combo exclusion, any improvement in quotes must come through other incentives or trading economics. This rule comparison does not measure execution quality.